Payday loans are legal in Oregon. See the limits, the real cost and your rights, then compare licensed lenders online or near you.
Oregon Payday Loan Regulations
Here's what fees you can expect when obtaining online payday loans in Oregon:
| Payday lending status in Oregon: | Legal |
|---|---|
| Maximum loan amount of a payday loan in Oregon: | Lesser of $50,000 or 25% of borrower's gross monthly income (typical loans much smaller, around $300) |
| Maximum Interest Rate (APR): | 36% APR cap + up to 10% origination fee per $100 (max effective APR ~153.77%) |
| Minimum payday loans term in Oregon (OR): | 31 days |
| Maximum loan term: | 60 days |
| Number of rollovers allowed: | Up to 2 renewals allowed, then full repayment required |
| Number of outstanding loans allowed: | One at a time |
| Cooling-off period: | 7 days between loans |
| Finance charges: | 36% APR cap + up to 10% origination fee per $100 (max $30) |
| Collection charges: | Restricted |
| Criminal action: | Prohibited |
| State Regulator: | Oregon Division of Financial Regulation (DFR) |
Table Data Updated: September 2026.
Above you can see what fees you can expect when obtaining online payday loans in Oregon.
Compare Payday Lenders in Oregon
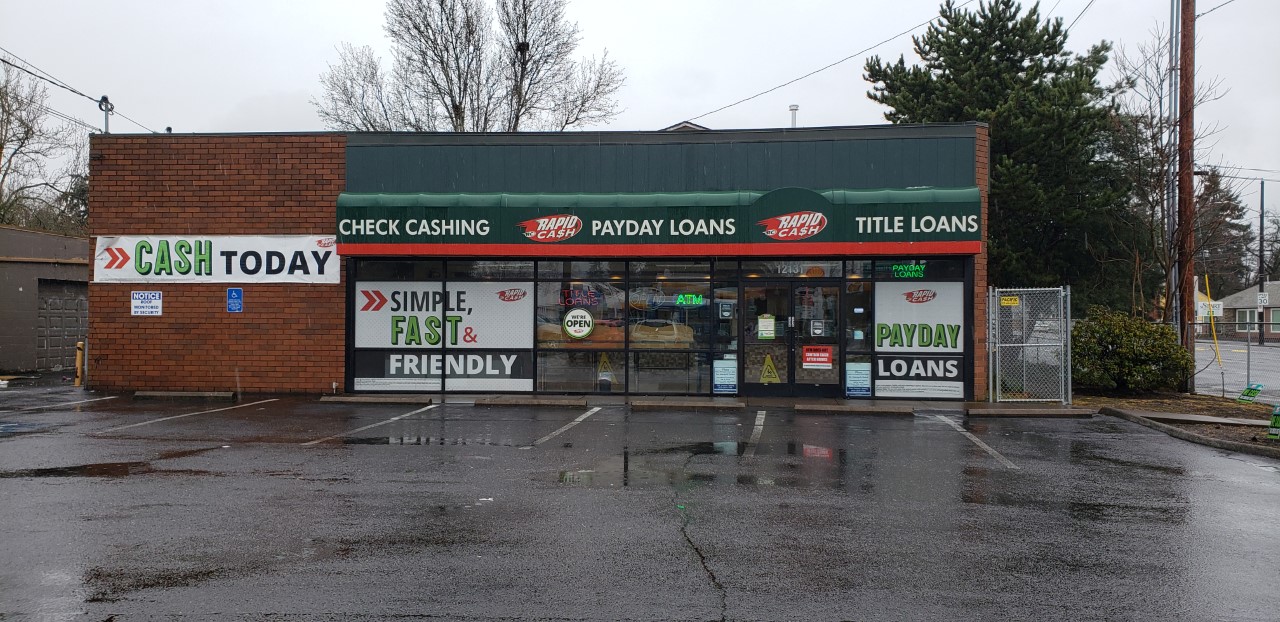
Payday Loans & Cash Advance In Oregon Near Me From Direct Lenders
Search 49 payday loan locations in Oregon by city or ZIP, or use your location to see the nearest first.
Biggest Cities for Payday Loans in Oregon
View All Cities →Are Payday Loans Legal in Oregon?
Yes. Payday loans are legal in Oregon and regulated by the Oregon Division of Financial Regulation (DFR). The limits in the table above come from state law, so check them before you borrow.

Always check the license
Before you apply, confirm the lender is licensed in Oregon on the Oregon Division of Financial Regulation (DFR) website. Ask for the total amount you will repay and the due date in writing.
Who Can Get a Payday Loan in Oregon?
Every lender sets its own rules, but a borrower in Oregon is usually an adult who can sign a loan contract, holds a government ID, receives regular income and has a checking account in their own name. A phone number and email address let the lender reach you.
Being approved is up to each lender. What no lender can change is the set of Oregon rules above: they cap what you may borrow and for how long.
How to Apply for a Payday Loan in Oregon
- Decide how much you need and check it against the Oregon limit above.
- Compare lenders and check each license.
- Read the offer: total repayment, due date, fees, what happens if you pay late.
- Sign only if the payment fits your next paycheck.
Common Reasons People Borrow in Oregon
Borrowers in Oregon usually need money for one thing that cannot wait: a car repair that keeps them from work, a medical bill, rent or a utility bill due before payday, or an overdraft they want to avoid. It works only when the repayment fits your next paycheck. If the same gap keeps coming back, a cheaper option from the list below is a better fit.
Why Use MaybeLoan in Oregon
- Free for borrowers: you never pay MaybeLoan.
- No loan decisions: the lender decides, not us.
- Lenders licensed in Oregon: check each license with the Oregon Division of Financial Regulation (DFR).
- How we earn: lenders may pay us when you apply through our links.
How Oregon Compares With Neighboring States
Payday lending rules change at the state line, and a loan follows the law of the state where you live. Here is how the states around Oregon treat payday loans:
| State | Payday loans |
|---|---|
| California | Legal: $300 Max, $255 in Hand |
| Idaho | Legal: 25% Income Cap |
| Nevada | Legal: 25% Income Cap, 35 Days |
| Washington | Legal: 30% Income Cap, 45 Days |
Online vs In-Store Payday Loans in Oregon
| Feature | Online | In-store |
|---|---|---|
| How you apply | Online form | Visit the store |
| Receiving the money | Bank deposit, timing set by the lender | Cash or check at the counter |
| When you can apply | Any time | Store hours only |
| Paperwork | Digital documents | Printed forms, ID in person |
| Questions | Chat, phone or email | Face to face with staff |
Online lenders need to be licensed in Oregon just like storefronts. A lender that says it does not need a license is a red flag.
Payday loans are expensive. State data for Oregon: 36% APR cap + up to 10% origination fee per $100 (max effective APR ~153.77%). Borrow only what you can repay from your next paycheck.
Cheaper Options Before a Payday Loan in Oregon
- Credit union loans. Federal credit unions can offer Payday Alternative Loans (PALs) with a capped interest rate. Ask a credit union you can join in Oregon.
- Paycheck advance from your employer or an earned wage access program, if your employer offers one.
- A payment plan. Utilities, landlords, doctors and many creditors will agree to a plan if you contact them before the due date.
- Local assistance. Call 211 or your county social services for help with rent, utilities and food.
- A small loan from a licensed lender. Compare the APR and the total cost, not only the monthly payment.
Who to Contact About a Lender in Oregon
Report a problem to the Oregon Division of Financial Regulation (DFR).
Sources: ORS 725A.010, Oregon HB 4116 (2026), Oregon DFR. Data last checked: 2026-09. This page is general information, not legal advice.
Example Cost of a Payday Loan in Oregon
Oregon caps the cost of this loan at 36.00% APR, plus a one-time origination fee. Actual rates, fees, approval, and repayment terms vary by lender and applicant.
| Loan Amount | Fee (31-day loan) | Total Due (31-day loan) | Fee (60-day loan) | Total Due (60-day loan) |
|---|---|---|---|---|
| $100 | $13.06 | $113.06 | $15.92 | $115.92 |
| $200 | $26.12 | $226.12 | $31.84 | $231.84 |
| $300 | $39.17 | $339.17 | $47.75 | $347.75 |
| $400 | $42.23 | $442.23 | $53.67 | $453.67 |
| $500 | $45.29 | $545.29 | $59.59 | $559.59 |
- Fee is calculated from the state's 36.00% annual cap: amount × (APR ÷ 100) × (days ÷ 365), plus the origination fee.
- This is an example based on Oregon's maximum legal rate - it is not a guaranteed offer.
- Actual terms, approval, and final cost are determined by the lender.
- Legal rate data last verified: September 2026.
Frequently Asked Questions About Payday Loans in Oregon