Installment loans are legal in Connecticut. See how the state regulates them, what they cost and how to compare licensed lenders online or near you.
Connecticut Installment Loan Regulations
Here's what fees you can expect when obtaining online installment loans in Connecticut:
| Installment lending status in Connecticut: | Legal |
|---|---|
| Maximum loan amount in Connecticut: | Up to $50,000 (Small Loan Act, Conn. Gen. Stat. 36a-555) |
| APR cap: | Under $5,000: the lesser of 36% APR or the Military Lending Act maximum. From $5,000 to $50,000: 25% APR. Late fee the lesser of 5% or $25 a month (36a-555, 36a-558) |
| Minimum loan term: | Not specified |
| Maximum loan term: | Not specified |
| Prepayment penalty: | A prepayment penalty is prohibited (36a-558) |
| State Regulator: | Connecticut Department of Banking |
Table Data Updated: October 2026.
Above you can see what fees you can expect when obtaining online installment loans in Connecticut.
Compare Installment Lenders in Connecticut
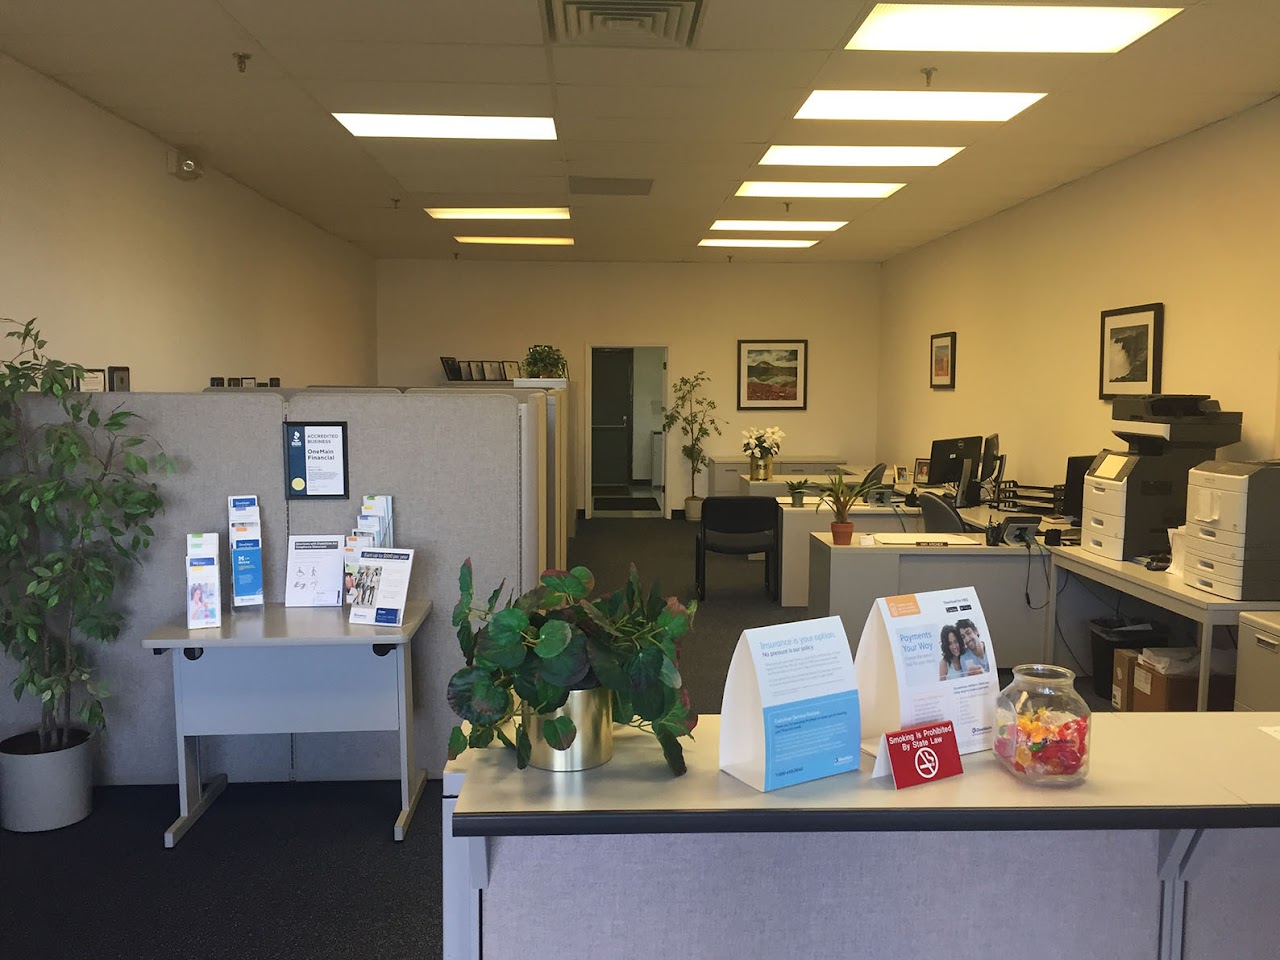
Installment Loans In Connecticut Near Me
Search 5 installment loan locations in Connecticut by city or ZIP, or use your location to see the nearest first.



Biggest Cities for Installment Loans in Connecticut
Are Installment Loans Legal in Connecticut?
Yes. Installment loans are legal in Connecticut and regulated by the Connecticut Department of Banking. Payday loans are not legally available in Connecticut, so a licensed installment loan is the regulated way to borrow and repay in several payments. See what the law says about payday loans in Connecticut. The limits in the table below come from state law, so check them before you borrow.

Always check the license
Before you apply, confirm the lender is licensed in Connecticut on the Connecticut Department of Banking website. Ask for the APR, the number of payments and the total you will repay in writing.
How Installment Loans Work in Connecticut
- You receive a set amount and agree on the number of payments.
- Every payment is the same size, due on a fixed schedule.
- The APR and fees decide the total you repay.
- Paying off early may or may not save interest, so ask the lender in writing.
Who Can Get an Installment Loan in Connecticut?
Before you apply, have these ready:
- Proof of regular income
- A checking account in your name
- A government-issued ID
- Your phone number and email
- You must be old enough to sign a contract in Connecticut
How to Apply for an Installment Loan in Connecticut
- Decide how much you need and how many months you can pay.
- Compare lenders and check each license.
- Read the offer: APR, fees, number of payments and total repayment.
- Sign only if the monthly payment fits your budget.
Installment Loans in Connecticut: Pros and Things to Watch
The upside is predictability: every payment is the same size and the loan ends on a known date, so it is easier to budget than a single repayment. The trade-off is time. The longer the term, the more interest you pay in total, and fees or prepayment rules can change the real cost. Read the agreement for both before you sign.
Federal law (the Truth in Lending Act) requires a lender to disclose the APR, the finance charge and the total of payments before you sign. If a lender skips this, treat it as a red flag.
Installment vs Payday Loans in Connecticut
| Feature | Installment loan | Payday loan |
|---|---|---|
| How you repay | Scheduled payments over weeks or months | One payment on the due date |
| Status in Connecticut | Legal, regulated by the Connecticut Department of Banking | Not allowed: Usury Limits |
| What to compare | APR, fees, number of payments, total repayment | Fee per $100 and total repayment |
| Early repayment | Ask whether a penalty applies | Usually due in full at once |
Common Reasons People Borrow in Connecticut
People in Connecticut usually turn to an installment loan for a cost that is too large for one paycheck: a repair, a medical bill, moving costs or a pile of small debts they want to repay in one schedule. It works when the monthly payment fits your budget for the whole term.
Why Use MaybeLoan in Connecticut
- Free for borrowers: you never pay MaybeLoan.
- No loan decisions: the lender decides, not us.
- Lenders licensed in Connecticut: check each license with the Connecticut Department of Banking.
- How we earn: lenders may pay us when you apply through our links.
The loan calculator at the end of this page lets you test different amounts and terms. Adjusting both helps you find a payment that fits your budget.
Installment loans can still be expensive. Compare the APR and the total repayment of every offer, not only the monthly payment, and borrow only what you can repay on schedule.
Cheaper Options Before an Installment Loan in Connecticut
- Credit union loans. Credit unions often lend at lower rates to members. Ask one you can join in Connecticut.
- Paycheck advance from your employer or an earned wage access program, if your employer offers one.
- A payment plan. Utilities, landlords, doctors and many creditors will agree to a plan if you contact them before the due date.
- Local assistance. Call 211 or your county social services for help with rent, utilities and food.
Who to Contact About a Lender in Connecticut
Report a problem to the Connecticut Department of Banking.
Sources: Connecticut licensed consumer finance law as cited in the fields: official text read 2026-10-13 (several pages through web.archive.org captures); evidence in docs/sources/regulators/installment/Connecticut.json. Data last checked: 2026-10. This page is general information, not legal advice.
Frequently Asked Questions About Installment Loans in Connecticut